Firm founder explains how a model built with women in mind differs from traditional wealth management
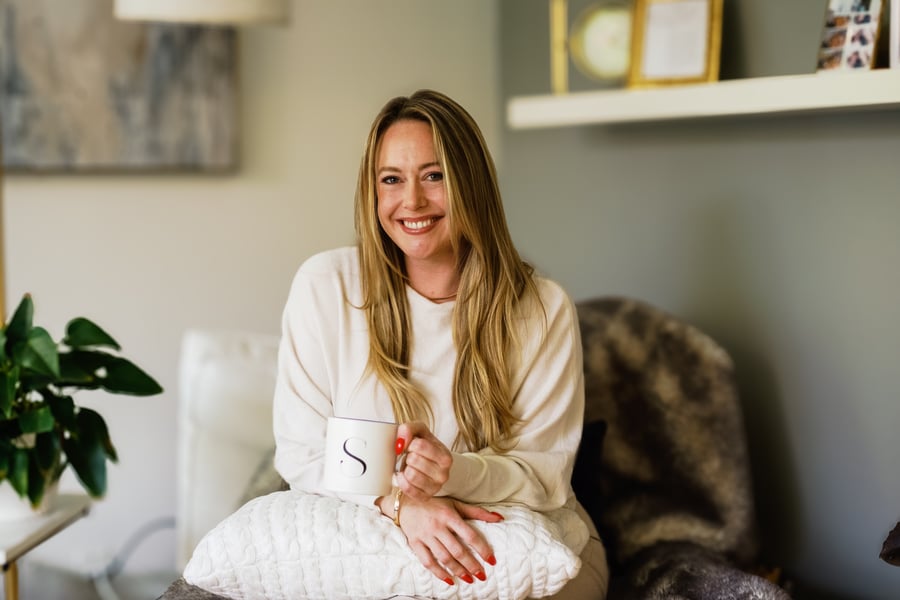
Stephanie O’Mahoney has heard wealth firms and advisors talk about bringing on more women as clients and advisors in the eighteen years since she started in the industry. In that time, working at some of the big banks, at Wealthsimple, and at independent advisory firms, O’Mahony hasn’t seen the needle move enough. She hasn’t seen a shift in the industry’s operating models meaningful enough to attract and support more women as clients or as advisors. So she’s starting her own firm.
Vale Wealth, that new firm, has officially launched in the Canadian market with O’Mahoney as its founder. Describing the firm as “unapologetically female-focused,” she says that she wants to reshape the way this industry approaches clients and the economics behind the industry’s offerings. To achieve that she’s using a differentiated service model offering, from per centage fee based private wealth service to a monthly subscription rate for planning services. While the goal is to serve women, O’Mahoney emphasizes that her firm will serve clients of all genders and that a model built around flexibility can help to solve some of the wider challenges that the industry faces.
“I want to flip the traditional wealth model on its head to actually serve the clients that we talk about wanting to serve so much,” O’Mahoney says. “The one question I kept on asking myself was ‘if women had started the financial service industry, what would it look like? What I kept on coming back to is that you’d feel really comfortable walking into any office. Fees would be really transparent and easy to understand. You would always be able to get your questions answered, and you’d have somebody that was going to hold your hand through the hardest days of your life. But even more than that, there wouldn’t be an account minimum for you to get really quality financial advice.
“What I think I’ve seen over and over in this industry is we talk about wanting to work with women, but we are not earning the relationship before women are wealthy.”
How a tiered model can serve women better
Vale Wealth’s three tiers of service are Vaile Private Wealth, a traditional wealth management offering for high net worth clients charging a per centage fee, Vale Access, which offers advice and planning without the requirement of moving an account and is targeted at Canadians navigating divorce, and Vale Checkpoint, which gives planning and advice to clients at specific moments in their lives. Both Access and Checkpoint charge a monthly fee of $300 with a minimum client commitment of one year.
O’Mahoney decided to offer a subscription fee model for Access and Checkpoint because as she puts it “a lot of women might not have the portfolio size to demand a really nice fancy advisor, but their problems are big enough.”
Vale Access is aimed at clients navigating a separation, an inheritance, or the sale of a key asset. O’Mahoney says that for people going through a divorce, a planner can be as valuable as a lawyer, because making sense of the assets one receives and how different a $1 million home and a $1 million RRSP can be for a plan. The subscription fee model allows for clients navigating those deeply challenging moments to get advice without having to move an account.
Vale Checkpoint was designed with the goal of building confidence. She notes a CIRO study released late last year which found that when presented with financial literacy questions, Women answered “I don’t know” more often than men. However, when presented with the same question without the option of saying “I don’t know” women scored the same as men on their tests. Confidence, rather than knowledge, appears to be one of the primary impediments to women’s success as investors. O’Mahoney believes that through a year of planning, education, and work with those clients as their advisor, she can build that confidence in women and give them a better platform as they start their careers or navigate other transition moments in life.
What the industry can learn from Vale’s model
O’Mahoney notes that while this kind of service offering was around the unique life stages, pressures, and social dynamics that many women go through, the same offerings could appeal to male clients as well. She expects to serve men in her practice, either as the spouses and family members of the women who join her practice, or on their own. The approach that was designed as women-first, she says, offers a kind of flexibility that could appeal to clients of any gender.
While being a woman and an advisor might make her appeal more to women, much as a female women’s health practitioner might be more desirable to their patients, O’Mahoney argues that the industry’s push to serve more women clients by simply hiring more women as advisors doesn’t interrogate the problem deeply enough.
“If it was as simple as just hiring more female advisors, I think it would have happened. But that assumes that there are female advisors to be hired. And I think that in the way that the industry has set itself up, it’s not a soft landing spot for women,” O’Mahoney says. “What was really stifling for me in that world was not even just the lack of female representation, it was just the lack of flexibility.”
O’Mahoney says that account minimums and the economics of per centage fee models made serving the kind of clients she wanted to work with more difficult. Moreover, she believes that by focusing only on the wealthiest clients, who for a long time have been men, firms haven’t set themselves up with strong relationships with women, who are projected to control roughly $4 trillion in wealth by 2028. She believes that more flexibility to serve women at the beginning of their careers and during some of the most difficult moments in their lives can create those deeper relationships. She says that serving these women and growing the asset management industry as a whole should involve questioning the AUM model itself.
“The AUM model is lucrative. I think we’re foolish to say otherwise,” O’Mahoney says. “But, there are a lot of different ways to have this make money. I want to see more advisors asking themselves if the AUM pricing model still the right thing in this business in this time for their clients. And if not, then I would like to see other firms get more creative with how we can serve people.”