Serving physicians showed me why niche fluency, full-service planning and transferable trust matter more than price or fees
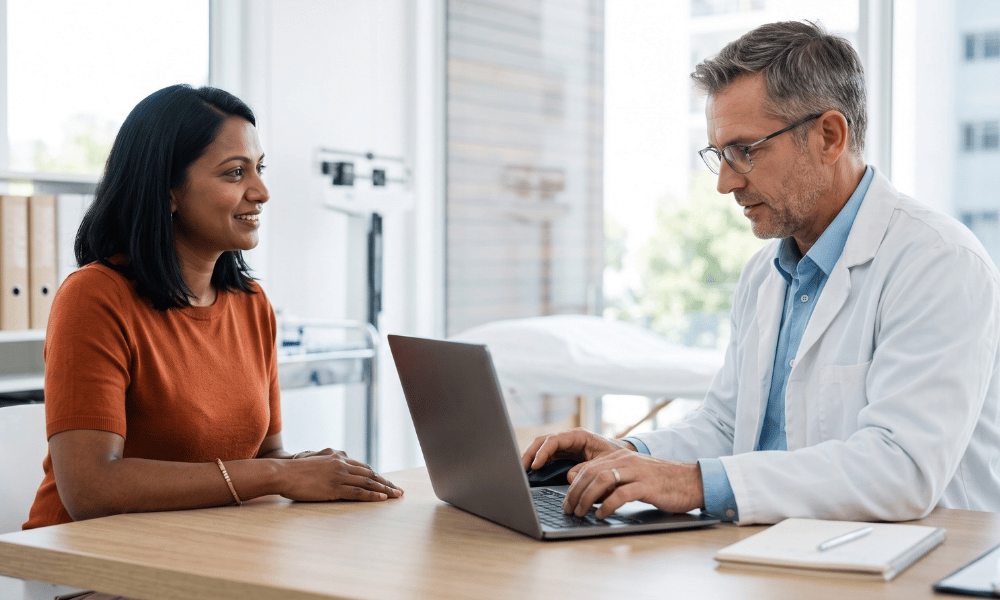
A few months into my career, a single conversation set the direction for everything that followed. At a networking event for senior and junior advisors, a planner with 35 years in the business told me business owners make ideal clients because they have nothing and need everything: no benefits and no pension. I didn't know many business owners at the time, but I did know several young physicians. So, I decided then and there that physicians would be my market, simply because they were the people I knew.
That decision grew into a specialized practice serving physicians and healthcare professionals, and the lessons apply to any financial advisor building around a niche.
Why physician clients need everything at once
The veteran advisor was right. Physicians have no pension, so they need Registered Retirement Savings Plans, tax planning, incorporation, Registered Education Savings Plans for their children, and disability, life and health insurance. Many also need group benefits for their medical practices.
Getting introduced can be a challenge. Once you are working with healthcare professionals, though, they tend to refer you to other healthcare professionals. Once you're in, you're in.
I see a clear polarization among physician clients. Some want to stay completely hands-off and delegate everything. Others want to manage their own investments, and that is where the significant blind spots emerge. Many physicians acknowledge that, as a group, they tend to be poor financial managers, even if few admit it about themselves.
I recently saw a client who had set up a child's education account incorrectly, and the government grants, including the Canada Education Savings Grant, were never received. With a financial planner involved, that is table stakes. When people set things up on their own, those gaps go unnoticed because they don't know what they don't know.
The irony is striking. Many physicians would strongly discourage patients from taking medical advice from the internet, yet readily take financial advice online. Sometimes the most valuable thing I can do for a young physician is show them what they don't yet know.
Succession planning is a trust transfer, not a transaction
My brother, Frank, and I work together, and we co-presented on succession planning for advisors at the Million Dollar Round Table (MDRT). The presentation covered every client type, but physicians sharpen the lesson.
Too many buyers focus on acquiring client assets. Physicians and other high-income professionals genuinely value their relationship with their advisor, much as they value one with their own doctor. When a succession treats them as a transaction, retention suffers.
A succession needs at minimum a one-to-two-year overlap in which the outgoing advisor personally introduces the successor to top clients, making clear this is not the highest bidder but someone deliberately chosen. You trust me, I trust them. That trust has to be transferable, which is why veteran advisors should chart a gradual and deliberate path to succession.
Most planners selling a practice discover it isn't ultimately about price. Fit in culture, shared values and background matters far more than the multiple, because the primary obligation is that clients are properly looked after. That priority is part of why succession planning is redefining the advisor-client relationship.
Specialization is how advisors raise the bar
Raising the bar starts with continued education, which often means becoming more of a specialist in investments, employee benefits, insurance, or estate planning. Specialization helps most when you can speak the language of the niche you serve. That fluency builds credibility, and credibility drives referrals.
It also means immersion in the niche community: the public events, fundraisers, and trade conferences where clients gather. Sponsor or volunteer at healthcare events, dental associations or construction industry conferences. When people see you in their world, you stay top of mind, and when they are ready for a financial planner, they think of you first.
Our own practice followed that path, evolving from a traditional book of business into an ensemble practice with dedicated specialists for employee benefits, estate planning and investments. It is far more valuable for a client to have seven or eight products and services with one firm than for a firm to have seven or eight single-product clients. One place for insurance, investments, pensions, and estate planning simplifies clients' lives, and for us it produces deeper relationships and very high retention.
That depth matters more as the industry changes. With more consumer education available, fee compression is by far the biggest shift I have seen. Fees are far more competitive than they were years ago, and for high-net-worth accounts they are declining fairly consistently. Understanding the real forces behind fee compression for advisors helps explain why breadth and fluency, not price alone, keep clients.
The advice I received in my first months still holds. Clients who need everything will reward the advisor who understands their world, serves them completely and protects that trust when it is time to hand it on.
Darren Ryan, CFP, CLU, is a financial planner and co-owner of Ryco Financial in St. John's, N.L.