The Montreal firm signs a 10,000 sq. ft. lease and plans to hire up to 30 staff
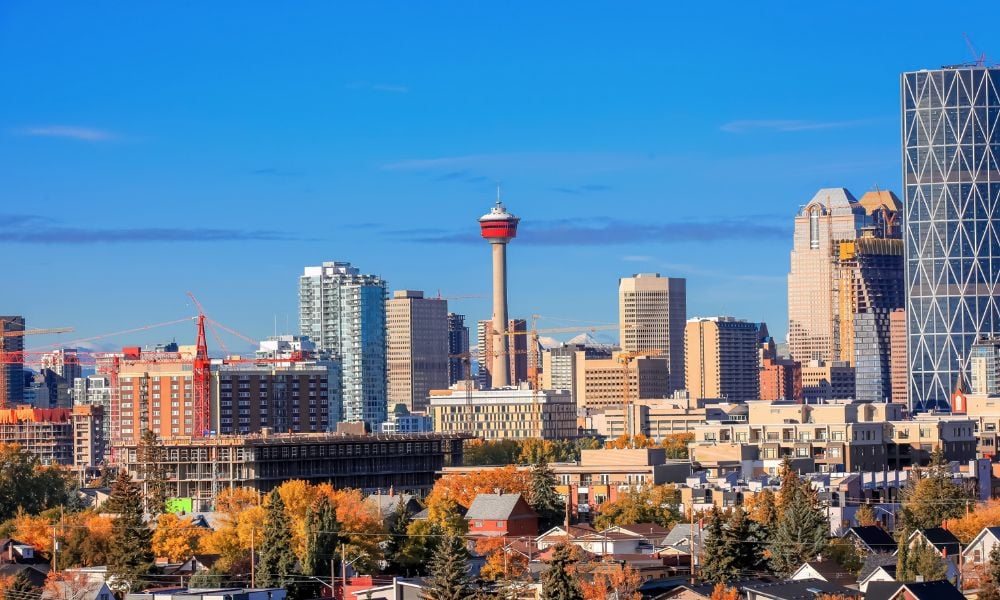
Montreal-based Richter Family Office is opening a Calgary office in the coming weeks as its roster of Alberta clients grows.
The firm has signed a lease on 10,000 sq. ft. at 400 Third, formerly the Devon Tower. It plans to hire 20 to 30 staff over the next year.
Richter manages about $12 billion in assets, mostly private wealth for entrepreneurs and their families rather than public companies, the Financial Post reported Thursday. Many of its clients have $50 million to $500 million in investable assets. It often sets a floor of $25 million to $30 million for new clients. The firm, which also has a presence in Toronto and Chicago, is owned by 77 partners and employs about 700 people across Canada.
“This has been probably one of the most prolific wealth creation areas in the country,” partner Michael Kaumeyer said in an interview at Calgary’s Ranchmen’s Club.
Partners named in June
In a June 4 news release, Richter announced that Kaumeyer and Errol Kuszner had joined as partners. Kaumeyer, who is rooted in Calgary, was to help anchor the firm’s Western Canada expansion. The firm said it already served clients in Alberta and British Columbia.
Founded in 1926, Richter marked its 100th anniversary this year. It describes itself as Canada’s only Business Family Office.
Ultra-wealthy ranks grow
Ultra-wealthy Canadians, defined as those worth US$30 million or more, number close to 13,000 this year. That is up about 20% from 2021, the Financial Post reported, citing Knight Frank. Knight Frank’s 2026 wealth sizing model put the global count at 713,626, up from 551,435 in 2021.
The wealth gap in Canada, meanwhile, continued to widen last year. Statistics Canada defines it as the difference in net worth share between the top 20% and bottom 40% of households. It reached 62.7 percentage points at the end of 2025, up 0.6 points over the year. The top 20% held 65.7% of household net worth, and the bottom 40% held 3.0%.
TD Economics reported in March that the gap narrowed by 5 percentage points from 2019 to 2023, to a record low of 60. It added that the gap had since stabilized.
Client focus
“We need more of these families in Canada,” Kaumeyer said. “We need more people building businesses, more people staying here, wanting to be here – not leaving the country.”
Partner Justine Delisle said the firm’s focus is on building strong client relationships. “It’s not about the number of clients,” she said. “We have been very careful in our growth.”
In Alberta, many clients are first-generation wealth creators who built their businesses in the province and have sold them or plan to pass them to the next generation. Kaumeyer estimated hundreds of Alberta families have assets above $30 million.
Many families want to pass their success to the next generation, Kaumeyer said. “This wealth can help empower that,” he said. “What we don’t want it to do, and what we’re trying to help families with, is not making it a thing of entitlement.”
Separately, DC Finance will host an invitation-only Alberta Family Office and High Net Worth Conference Oct. 13.
Cost pressures elsewhere
Higher energy prices tied to the war in Iran have pushed up costs for many Canadians. The Parliamentary Budget Officer’s June outlook noted the war had ballooned fuel pricing, The Canadian Press reported.
Eric Wulder, a personal financial advisor at Edward Jones in Calgary, told the Financial Post that some clients are under strain. “There’s a big question mark hanging over a lot of people in terms of what things are going to look like a year from now,” he said.
Even clients who are often middle- or upper-middle-class are “feeling pinched” by higher costs, debts and incomes that do not cover it all, Wulder said. “We’re seeing a lot of people make choices to fix instead of buy something new,” he said.