Capco's Matt Berkowitz tells Wealth Professional Canada that aggregating client data is no longer enough.
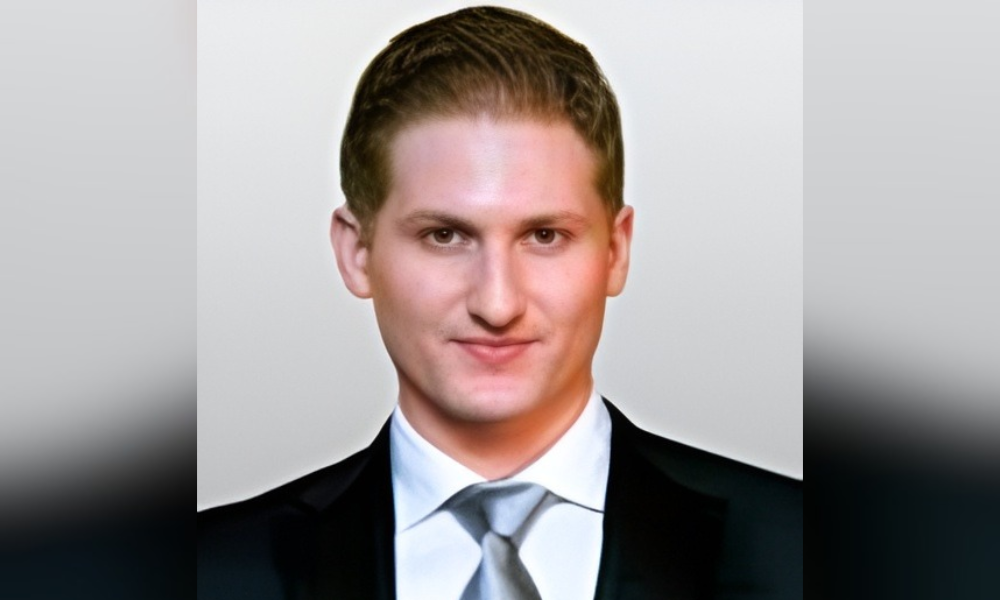
The wealth management industry has spent years building consolidated views of the client, but according to Matt Berkowitz, managing principal at Capco in New York, that work is now largely done - and largely beside the point.
"I think we're approaching the point where having a consolidated view of the client is no longer a differentiator," Berkowitz said. "It's becoming the price of admission."
Berkowitz advises firms across the wealth management industry on technology strategy and operating model transformation. His view is that putting more information on one screen does not make an advisor more effective. He believes that the next competitive advantage is knowing what matters, when it matters, and what to do about it.
From visibility to anticipation
The concept of client 360 with a unified dashboard drawing together CRM, portfolio management, financial planning and other data sources, has been a fixture of wealthtech conversations for most of the past decade. Firms have invested heavily in it. But Berkowitz draws a clear line between what that investment achieved and what it has not.
While firms have bcome better at collecting client data in one place, he says they have not solved the harder problem of making it useful at the moment it matters. The CRM holds the relationship, the portfolio system holds the investments, the planning tool holds the goals - and the advisor is still expected to connect those threads manually.
“Consider a client approaching retirement who also has concentrated stock exposure, an upcoming liquidity need and an estate plan that hasn't been revisited in years,” he said. “A traditional Client 360 platform might display all that information. An intelligent platform should recognize how those circumstances intersect, identify potential risks or planning opportunities, and help the advisor determine the next appropriate conversation.”
That requires moving beyond aggregation into what Berkowitz calls contextual intelligence: connecting information across systems, interpreting it against client goals, and embedding relevant insights directly into the advisor's workflow. As platforms like those highlighted in WP's coverage of IGM Financial’s AI push and what it signals for Canadian advisor platforms demonstrate, the industry is actively grappling with how to close it.
The hidden cost of disconnected systems
The cost of disconnected systems, Berkowitz says, is widely underestimated because most of it is invisible in day-to-day advisor activity.
"Firms often underestimate the cost because much of it is hidden in everyday advisor activity," he said. "It's not simply time spent navigating applications. It's the cumulative impact on advisor capacity, missed opportunities and the consistency of the client experience."
A client with a concentrated stock position approaching a vesting event illustrates the problem. The portfolio system understands the exposure. The planning tool may flag a diversification or tax-planning need.
The CRM holds the client's broader financial priorities. But if those systems are not connected intelligently, the advisor must recognize the relationships themselves, assemble the information manually, and decide when to act.
The consequences compound. Advisors spend time assembling rather than engaging. Service quality becomes dependent on individual advisors rather than firm-wide systems. And planning conversations that require a timely prompt may happen too late - or not at all.
"The real cost of disconnected technology isn't just operational inefficiency," Berkowitz said. "It's the advice that never gets delivered because nobody connected the dots in time."
That framing aligns with WP’s reporting on Mackenzie Investments and OneVest’s platform overhaul, which has tracked how firms are attempting to reduce the manual labor of toggling between systems - with uneven results.
What genuine data activation looks like
Berkowitz distinguishes between firms that have integrated data and firms that have integrated decision-making. The difference, in his view, comes down to whether technology changes what an advisor does, not merely what an advisor can see.
"A platform that genuinely activates data should surface relevant insights, explain why they matter, recommend appropriate next steps and connect those insights to executable workflows with advisor oversight," he said.
The feedback loop matters as much as the initial insight: Did the advisor act? Did the client engage? Did it improve a planning decision? These are the metrics Berkowitz thinks firms should care about - not the number of connected systems or alerts generated.
"Relatively few firms have achieved this maturity consistently across the enterprise," he said. Progress is visible in areas such as meeting preparation and portfolio monitoring, but intelligence that spans the full client relationship remains challenging.
The organizational barriers, in his view, are as significant as the technical ones. Wealth management firms are typically structured around products, platforms and channels with separate leadership, priorities and success metrics for CRM, investments, planning and banking. Clients do not experience their financial lives through those silos.
"That disconnect matters because generating an insight is only valuable if someone is accountable for acting on it," Berkowitz said. "Without clear ownership and alignment, sophisticated technology risks becoming another feature advisors are expected to adopt on top of everything else."
The firms that ultimately differentiate themselves, he argues, will not necessarily be those with the most sophisticated artificial intelligence. They will be the ones that redesign how people, data, technology and processes work together - a theme WP’s coverage of FNZ Advisor AI and what embedded intelligence means for Canadian advisors and others making large-scale bets on unified intelligence layers.
"Advisors bring judgment, trust and personal knowledge of clients that technology cannot simply replicate," Berkowitz said. "The objective should be to enhance those capabilities, not replace them."