Chipmakers led the rout as Democrats’ midterm sweep clouded the data centre outlook
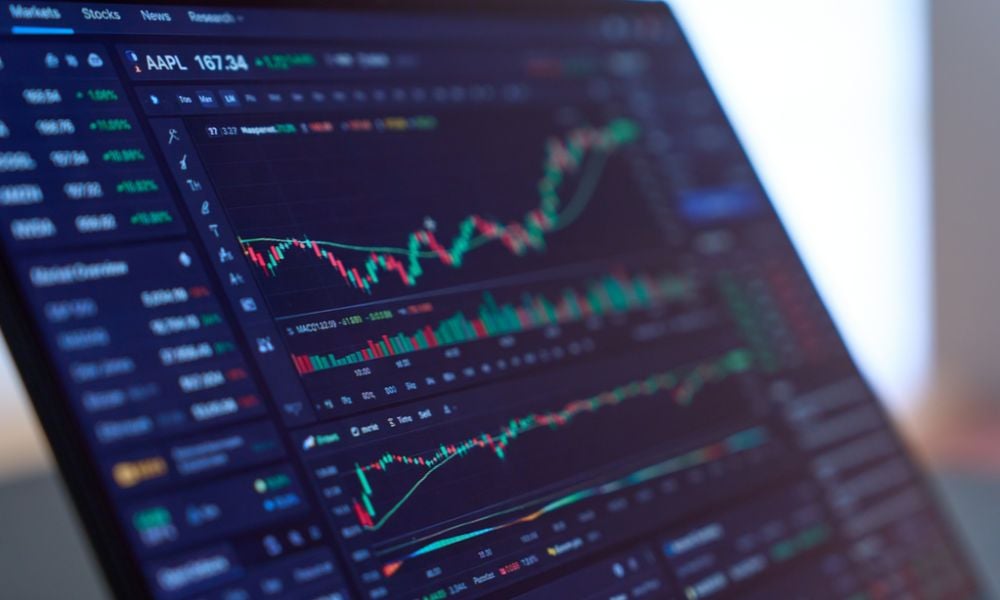
The Nasdaq Composite closed at 24,315.00 on Thursday more than 10 percent below its October 6 record close of 27,599.89, confirming a correction in the US market.
The S&P 500 fell 4.36 percent to 7,353.73 and the Dow Jones Industrial Average shed 1,833.06 points, or 3.44 percent, to 51,523.06, CNBC reported.
All three averages posted their worst day since April 2025, erasing Wednesday’s post-election rally.
Reuters put the value destroyed across S&P 500 companies at US$3tn.
Nvidia fell 9.3 percent and turned negative for 2026, now down 2.6 percent year to date, according to AP, which reported that a 1 percent move for Nvidia has more effect on the S&P 500 index than a 1 percent move for nearly any other US stock.
The Philadelphia SE Semiconductor index plunged more than 12 percent, Reuters reported, with Advanced Micro Devices down 17.3 percent and Broadcom down 10 percent.
CoreWeave lost almost 10 percent and Applied Digital fell more than 14 percent.
Meta Platforms slid 4 percent, while other large-cap technology stocks also lost ground, with Amazon.com and Alphabet each dropping 2.2 percent.
All 11 S&P 500 sectors closed lower.
Information technology fell 7.30 percent, its worst daily performance since March 16, 2020, CNBC reported.
Volume on US exchanges reached 26.9bn shares against a 20-session average of 17.7bn.
Reuters reported the most closely watched gauge of anxiety, the Cboe Volatility Index, rose 11.75 points to an eight-month high of 28.36 before closing at 28.18, its biggest intraday jump in more than 18 months.
Put premiums ran at about two times typical levels across index products, according to options analytics service Mercury Alerts, cited by Reuters.
Leveraged exchange-traded funds were expected to sell about US$47bn of stocks into the close, Nomura said in an intraday note reported by Reuters, which would be the second-largest amount in Nomura’s data going back to July 2006.
A Goldman Sachs prime brokerage report sent to clients on November 5 said large multi-strategy hedge funds were down “significantly” because of outsized exposure to large AI stocks.
Retail investors were on track for their largest day of selling across single stocks since the COVID-related crash, Viraj Patel, global macro strategist at Vanda Research, said in an intraday note reported by Reuters.
“On a typical sell-off, retail buy the dip. Today, that bid has effectively disappeared from individual names,” Patel said.
Democrats won control of both chambers of the US Congress in the November 3 midterm elections, Reuters reported, including in states where opposition to new data centres has mounted.
CNN reported that Texas governor-elect Gina Hinojosa campaigned on a temporary data centre moratorium and on eliminating certain tax incentives for data centre construction in the state.
Melissa Brown, global head of investment decision research at SimCorp, told Reuters that investors “appear to be recognizing” that some newly elected members of Congress and governors want to slow the pace of AI infrastructure development.
Brown said a slowdown would raise concerns because the AI growth story has depended on rapid buildout, even if those officials cannot stop it altogether.
Jed Ellerbroek, portfolio manager at Argent Capital Management, told Reuters the move looked like “the capitulation phase for the data center capex beneficiary stocks, especially the semiconductors,” adding that “the magnitude of the moves is outsized.”
The yield on the 10-year US Treasury fell to 4.84 percent from 4.90 percent late Wednesday, AP reported.
Cleveland Federal Reserve president Beth Hammack and Richmond Fed chief Thomas Barkin hinted at possible future rate hikes in comments on Thursday, according to Reuters, with US October nonfarm payrolls data due Friday.
Following the sell-off, the S&P 500 remains up 7.4 percent in 2026 and the Nasdaq up 4.6 percent.